Learn to spot "manufactured" documentation, occupancy misrepresentations, and DIY income or asset inflation from borrowers desperate to secure a property they intend to live in.
Discover how to identify internal red flags, such as debt omission schemes, altered bank statements, and improper appraiser pressure used by industry insiders to push unqualified loans to the closing table.
Protect your brokerage from coordinated criminal schemes, including straw buyer rings, reverse mortgage elder abuse, and equity skimming designed to steal massive amounts of cash from lenders and vulnerable homeowners.
Understand the Equal Credit Opportunity Act (ECOA), how to prevent disparate impact, and the critical importance of words when discussing neighborhoods.
Master the rules around accessing, using, and safeguarding consumer credit information, including proper adverse action procedures.
Understand how to properly collect, store, and safeguard nonpublic personal information (NPI) while maintaining compliance with FTC Safeguards requirements and cybersecurity protocols.
Understand the Bank Secrecy Act requirements, how to identify money laundering red flags, and the exact protocols for filing Suspicious Activity Reports (SARs).
Learn to identify and prevent Unfair, Deceptive, or Abusive Acts or Practices in your marketing, sales pitches, and borrower communications.
Navigate the Loan Originator Compensation rule to ensure compliance regarding how and when MLOs can be legally paid.
Learn the strict rules governing communications with appraisers and AMCs to ensure unbiased, compliant property valuations.
Master the rules surrounding kickbacks, Section 8 violations, and the proper, timely handling of settlement cost disclosures.
Learn the exact requirements for accurate data collection on the Loan Application Register (LAR), especially during face-to-face interviews.
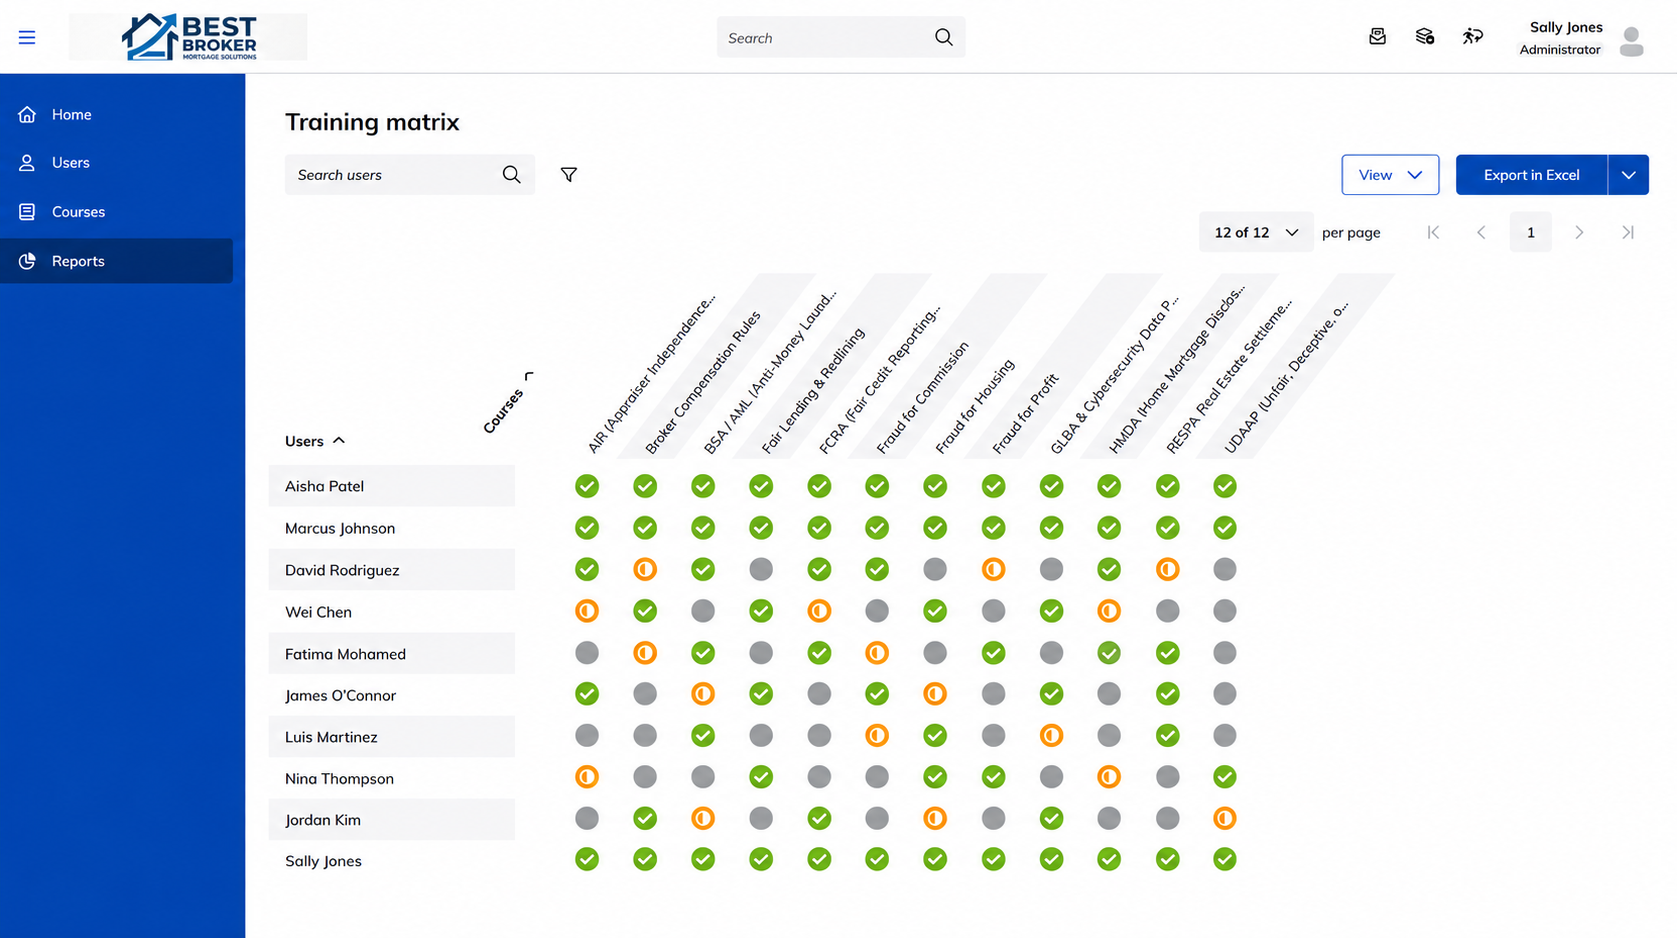
Fair Lending laws make it critical that your staff doesn’t accidentally steer clients or make inappropriate comments. A single off-hand remark by a receptionist or LO can trigger a discrimination lawsuit and a devastating CFPB audit.
Back office staff must understand the strict 30-day timeline for issuing denial (adverse action) letters. Missing this window carries steep per-violation fines, even on loans you never actually submitted to underwriting.